“The Squeeze and the Opportunity: SBA’s New Rules and the Mid-Market Hotel Trade”
Key takeaways
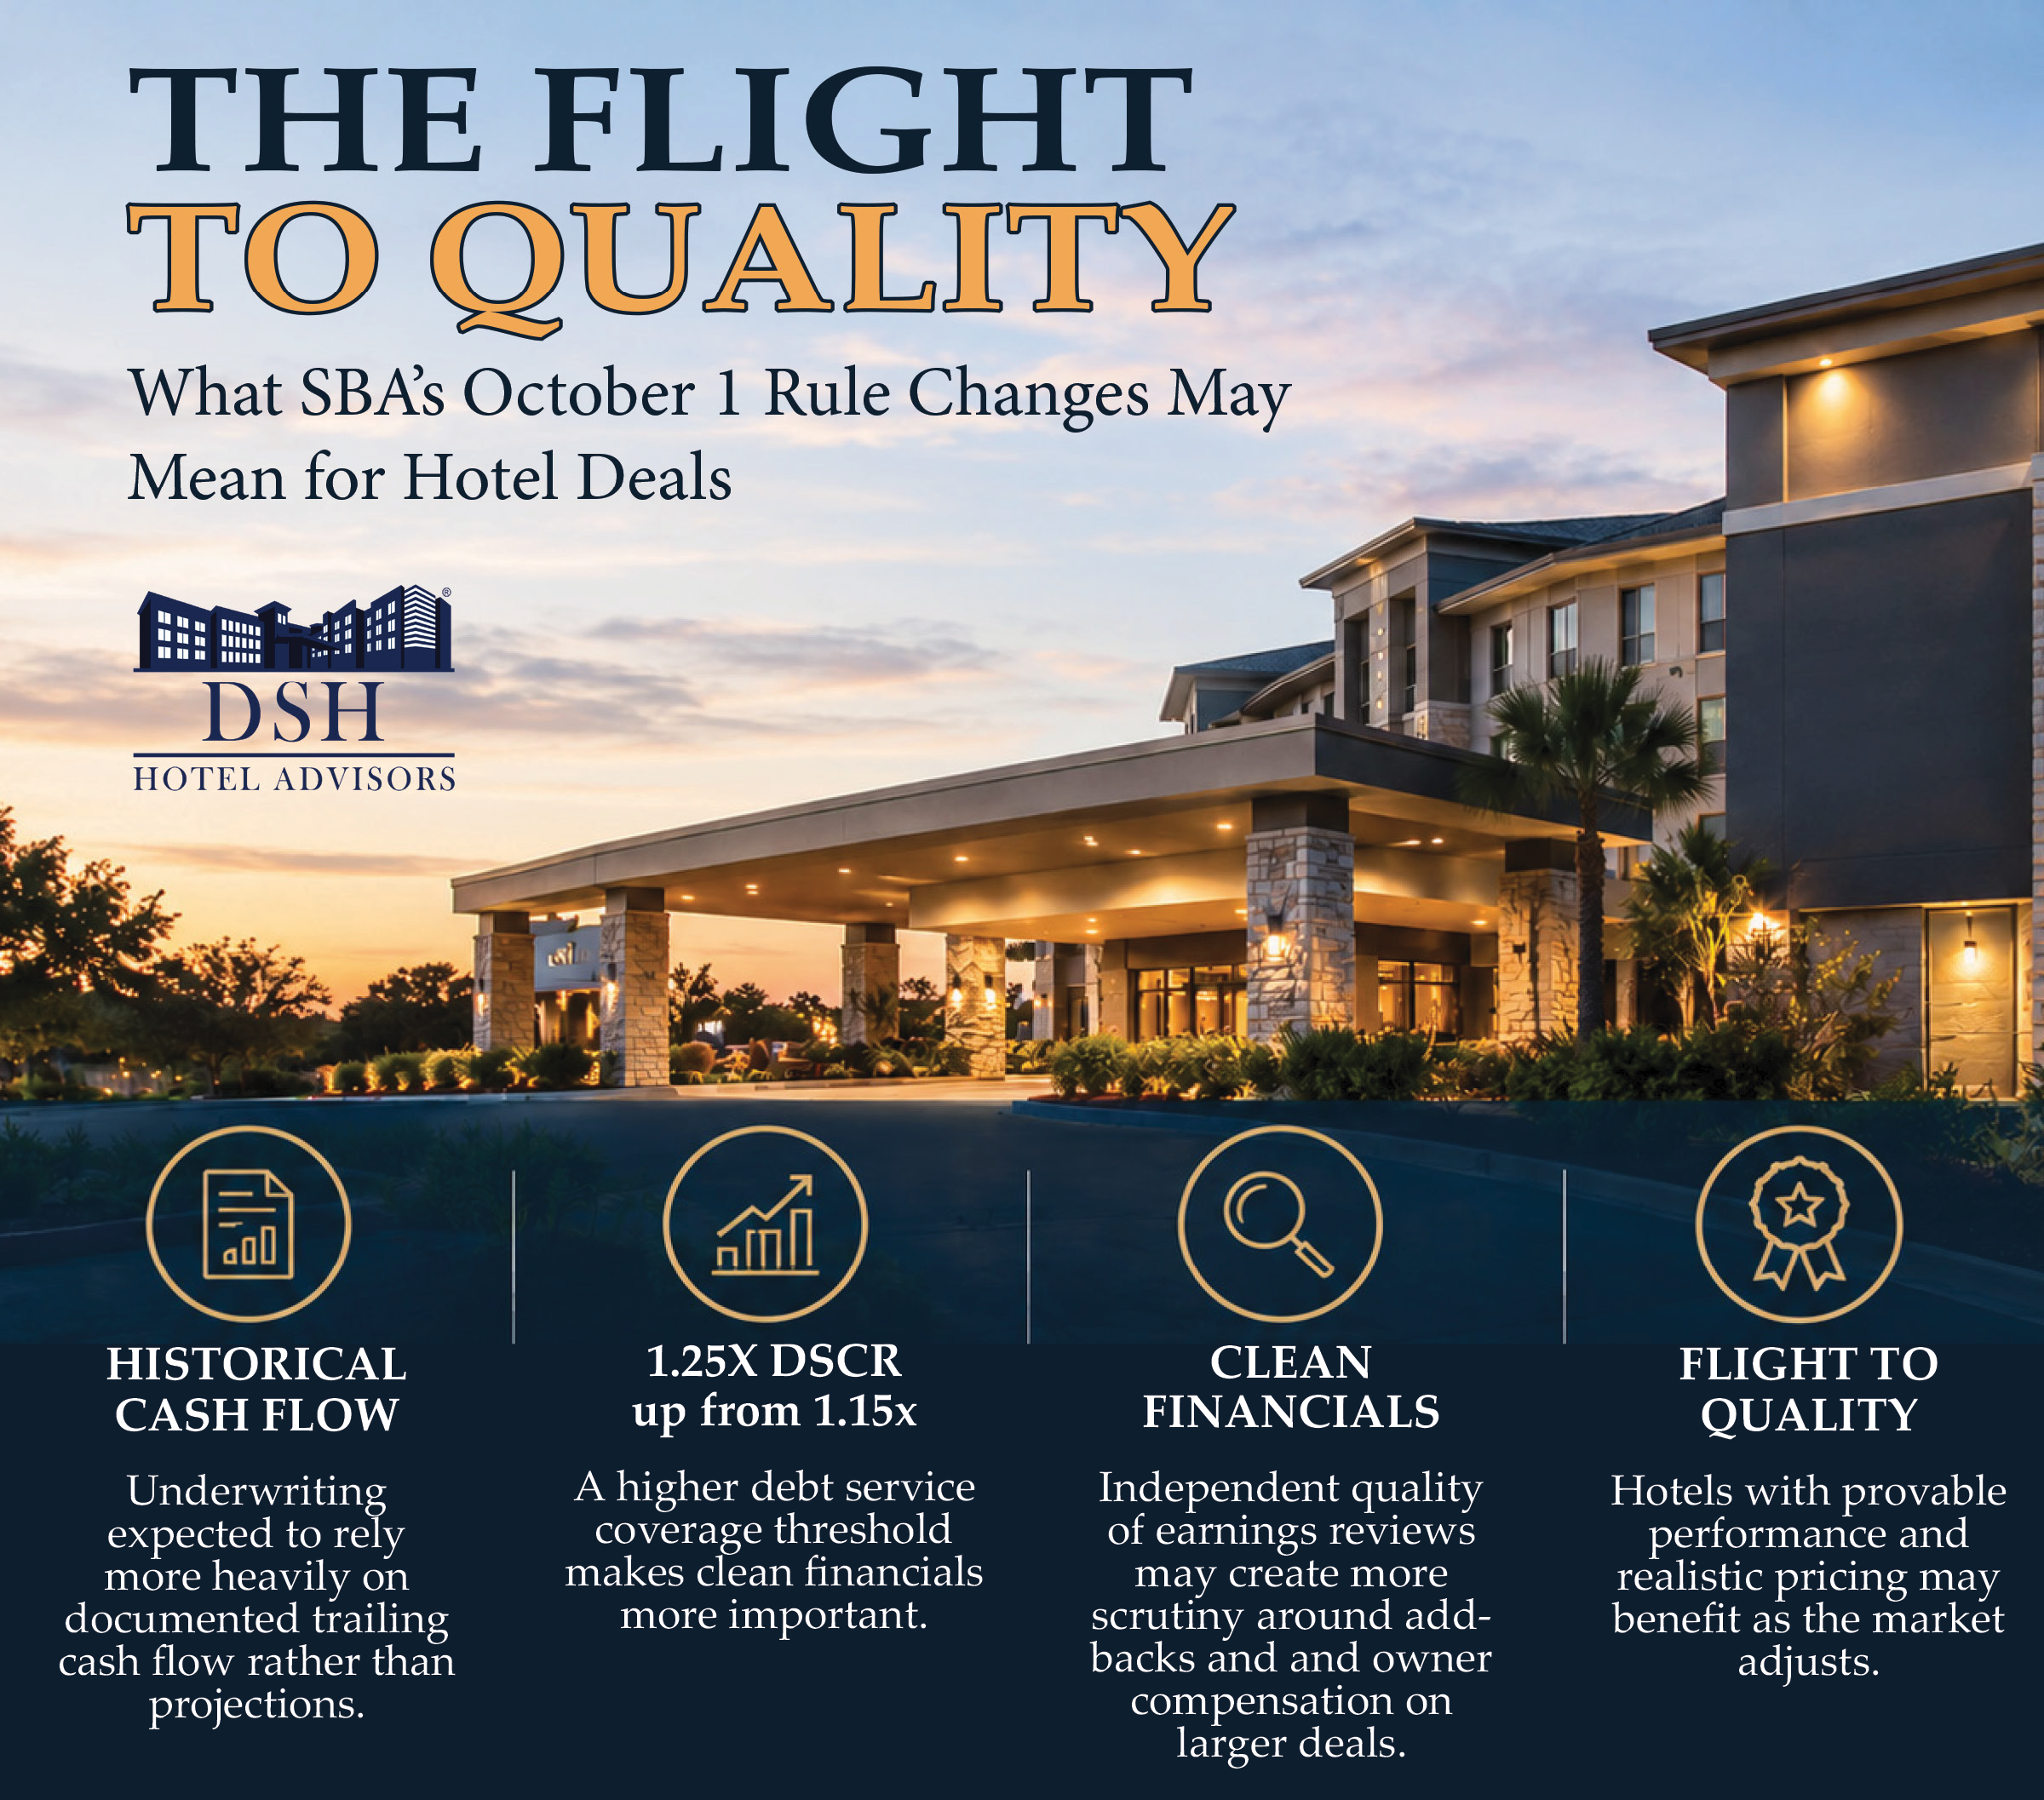
- SBA hotel acquisition underwriting is expected to rely more heavily on documented trailing cash flow rather than projections.
- The debt service coverage threshold is moving from 1.15x to 1.25x, making clean financials more important.
- Independent quality of earnings reviews may create more scrutiny around add-backs and owner compensation on larger deals.
- Seller financing may become less useful as a bridge if payment structures are treated more conservatively in underwriting.
- Hotels with clean books, provable performance, and realistic pricing may benefit from a flight to quality.
- Buyers and sellers who evaluate their position before October 1 may have an advantage as lenders adjust.
- Some unknowns remain, as it’s still early and lenders are still finalizing how they’ll navigate the new rules
Starting October 1, the SBA is slated to rewrite how it considers underwriting on change-of-ownership acquisitions, and from what we’re tracking, there is some potential good news among the cloudy headlines – depending on your perspective. Here’s the broad picture, and what it might mean whether you’re buying, selling, or just trying to read where the market’s headed.
The headline change, in plain terms: lenders may no longer be able to use wide projections to prove a SBA deal cash flows. It has to work with what the hotel actually did, a departure from what it might do after a renovation or a rebranding, and the bar for that is moving from 1.15x to 1.25x in debt service coverage ratios. Add-backs and owner pay are set to get checked by an independent quality of earnings report instead of a broker’s recast on larger deals. This would be by third party providers engaged by the lenders – not unlike the appraisal process. And seller financing, long used to bridge a pricing gap, appears to lose a lot of its usefulness under the new rules, since a seller note that doesn’t require real payments now gets treated as if it pays down fast for underwriting purposes, whether it actually does or not.
None of these sound huge on their own. Together, they look like something bigger, deserving of more context and collective attention.
A squeeze from two directions, as we see it
What makes this moment interesting, from where we sit, is that the pressure isn’t coming from just one place.
On one side, hotels that have been recently trading on the strength of a stabilization story, post-PIP upside, a brand conversion plan, a rate repositioning thesis, look to be more challenging in their ability to underwrite that story into the price. That doesn’t make those hotels unsellable. It likely means the buyer pool for them narrows to whoever can bring required equity, sellers becoming more aligned with the market in their pricing expectations, and the hotels which are clearing the bar on trailing performance alone start looking relatively more attractive by comparison.
On the other side, the broader credit market is tightening too. Higher rates have made conventional and CMBS debt more expensive, and banks carrying heavy hospitality exposure seem to be getting pickier. That combination looks like it’s quietly pushing some buyers who’d normally chase bigger deals down into SBA-eligible territory, where a government guarantee still makes financing workable even with rates where they are.
Put those two things together and the pattern we’re watching for is more demand chasing a pool of hotels that can actually prove their cash flow on paper. We don’t think that’s a reason to be pessimistic. It’s a reason to pay attention to exactly where your property, or your buy-side aspirations, sits inside that space!
For buyers: disciplined underwriting looks like an advantage right now
Deals with clean, provable trailing performance over the last two to three years, well-documented expenses, and light reliance on seller financing to close a gap seem likely to move through SBA lender underwriting with a lot less friction than they would have a year ago, and with less competition from buyers whose numbers can’t hold up. Hotels have long carried a heavier equity requirement than most other small business categories, so buyers who came in well-capitalized were already a step ahead, and that edge looks like it’s about to matter more now that the cash flow and earnings tests have tightened on top of it.
The hotels that clear this bar aren’t necessarily the flashiest ones on the market. They’re the ones that were run cleanly the whole time!
For sellers: get ahead of your own story
This is the part that matters most right now, and it’s worth treating with constructive conversations, not warnings.
Every hotel has a position in this shifting landscape, whether ownership has thought about it yet or not. If your trailing performance genuinely backs up the number you have in mind, with real documentation, you’re likely in a strong spot, and the market looks set to help support that more than it has in years. If your value has been leaning on a stabilization story, heavier add-backs, or a seller note to close a gap, none of that makes your hotel unsellable. It just means the time to deal with it is before it lands on a lender’s desk. Getting a real read on those metrics before you list means your sense of where the property stands is based on actual data, not guesswork. There is no better value in a shifting landscape than partnerships with guidance.
Practically, that looks like cleaning up how personal expenses flow through the books, backing up add-backs with documentation instead of just narratives, and being open to what trailing cash flow supports under the new math. Sellers who do that work now are likely to have a smoother path to close than sellers who find out where they stand for the first time during underwriting.
The grey area: reason for confidence, not alarm
It would be easy to read all this as the market just getting harder to work in. That’s not our read, and there’s real data behind why.
SBA’s own explanation for tightening this lending says acquisition loans have grown into one of the biggest categories of 7(a) lending, and the agency wanted to underwrite that more formally. But the agency’s own FY2025 numbers tell a more reassuring story: acquisition lending posted 8.29 billion dollars in volume with a 1.93% default rate, which actually beat the 2.71% default rate on everything else the SBA lends on. That doesn’t look like a broken category getting punished. It looks like a fast-growing one getting a more formal set of rules.
There’s also a track record worth watching for a pattern. This is the third SBA rulebook rewrite in about sixteen months. Lenders adjusted to each of the last two without acquisition lending disappearing, structures shifted, but the deals kept closing. We’d expect something similar to play out here, a stretch of adjustment through the fall, then a market that settles into the new rules the way it generally has before. The hotels and buyers who come out ahead will likely be the ones treating this as something to structure around now, rather than a reason to sit on the sidelines.
Why you haven’t heard more about this yet
If you’ve been expecting more noise, senators weighing in, trade magazines running headlines, the way SBA’s citizenship rules made real political waves earlier this year, you’ve probably noticed it hasn’t happened here. Worth thinking through why, because it looks like a timing edge more than a reason for doubt.
The citizenship and residency rules touched immigration policy directly, an easy, quotable subject for lawmakers. A debt coverage ratio moving from 1.15x to 1.25x just doesn’t carry the same impact, even though it may reshape a lot more deal flow in practice. What reaction there is has been real, it just looks contained to SBA lenders, our conversations with mortgage brokers, and other trade circles so far, rather than spilling into the mainstream. Because the rule doesn’t come into effect on loan applications/numbers until October 1, nobody’s actually been turned down under it yet. The louder public reaction to the last major SBA rewrite built up over months, as real borrowers hit real denials. That hasn’t had time to happen here.
If you’re trying to figure out where a specific hotel, or a specific acquisition, lands in this shifting framework, that’s exactly the conversation worth having with us before October 1st.
By Matt Lawrence / DSH Hotel Advisors